Creator Economy M&A: Q3 2026 Transaction Comparables Report
RockWater Roundup
Join our community of builders and investors, and sign up here for the most widely-read newsletter on M&A and strategy insights for the creator economy and social agencies.
We help you buy, sell, and invest better.
————
Hi readers,
Welcome to the third edition of our Quarterly Transaction Comparables Report.
Some takeaways from Q3; Ad Tech + SaaS was the busiest category with nine deals, headlined by Nielsen’s $2.15B agreement to acquire DoubleVerify. Platforms kept buying the tools creators use every day (Whatnot bought Shaped, Razer bought StreamElements, Flipboard bought Graze), while agencies went shopping for social-commerce specialists that sell through TikTok Shop and Amazon. In media, premium independent brands commanded real capital, with RedBird Capital taking a majority stake in Puck at a $250M valuation.
Scroll down for the full comps.
None of these takeaways are worth much without the data underneath them, which is why we build this report in the first place. Our goal is straightforward: build the most useful, credible dataset of M&A activity and public company benchmarks at the intersections of the creator economy we work in every day; talent management, marketing and advertising agencies, media publishers, audio and podcasting, commerce, ad tech, and content platforms.
There is no single great source of truth for deal activity in our industry. Valuations live scattered across press releases, private databases, and secondhand chatter. The existing aggregators either miss our niches entirely or bucket them into categories too broad to be useful. We built this because we’ve needed it ourselves: for pricing conversations with clients, buyer-seller benchmarking, and shaping market narratives in our daily M&A work.
If it’s valuable to us, we think it will be to you.
RockWater runs sell-side M&A processes across the creator economy and social agencies every week. We live these deals. This report is our attempt to bring more rigor and transparency to an industry that needs both, and it’s a natural extension of what we already publish through our weekly newsletter, LinkedIn deal breakdowns, and video commentary.
A quick note on what’s inside:
“Creator Economy” has become an increasingly amorphous term. As creators diversify their businesses and blur the lines between content, commerce, and culture, they’re less a niche vertical and more simply the economy.
To make sense of it, we built a framework of seven subcategories, designed to be mutually exclusive and collectively exhaustive. It’s imperfect and will evolve with the industry, but it’s a useful lens on an otherwise unwieldy space:
- Talent Management — Managing creator careers, sourcing revenue, and building long-term brand equity.
- Advertising Agencies — Deploying advertiser media spend into creator-driven content.
- Media Publishers — Producing and distributing creator content at scale.
- Audio — The ecosystem built around podcasting as a distinct subset of the creator economy.
- Commerce — Enabling the development and distribution of physical and digital creator products.
- Ad Tech + SaaS — The infrastructure powering content creation, distribution, and advertiser solutions.
- Content Platforms — The digital destinations where consumers go for creator content.
If you find this useful, the best thing you can do is share it and subscribe. We publish free weekly analysis in our newsletter, cover live deals on LinkedIn, and keep our full body of work — event recaps, deal videos, thought leadership — on our website.
Spot a deal we missed? Disagree with a category? Have a dataset you’d be open to sharing or partnering on? Tell us: hello@wearerockwater.com.
— Chris Erwin
Founder, RockWater
— Micheal Booth
Partner, RockWater
The Report
Inside: deal activity and public company comps across seven creator economy subcategories — 30+ M&A transactions and 30+ public comparables from Q3 2026.
A few things that stood out:
- Infrastructure led the quarter. Ad Tech + SaaS was the busiest category with nine deals, headlined by Nielsen’s $2.15B agreement to acquire DoubleVerify. Platforms kept buying the tools creators use every day: Whatnot bought Shaped, Razer bought StreamElements and Flipboard bought Graze.
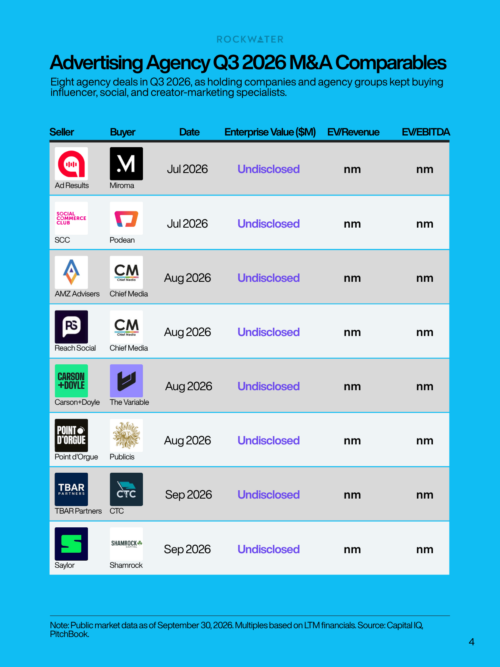
- Agencies bought into social commerce. Eight agency deals, many targeting TikTok Shop and Amazon specialists: Podean bought Social Commerce Club, Chief Media bought Reach Social and AMZ Advisers, and Shamrock Capital took a majority stake in Saylor.
- Premium media commanded real capital. RedBird Capital took a majority stake in Puck at a $250M valuation, and creator-led companies showed up as consolidators, most visibly Jake Paul’s Most Valuable Promotions merging with the PFL.
- Talent management stayed quiet. Only three deals, short of the Q1-level rebound we expected heading into the quarter.
—> Read the full Q3 2026 Transaction Report
Below: a preview of what’s inside.
—> Read the full Q3 2026 Transaction Report
New here? Subscribe to the RockWater newsletter for weekly creator economy M&A analysis.
We’re RockWater Industries. We do M&A and strategy advisory for creator economy and social / audio agencies. From buy / sell-side M&A to go-to-market planning.
DM us on LinkedIn or email our founder at chris@wearerockwater.com